
Industries
"AI Chatbot for Mortgage Brokers: Capture Home Loan Enquiries Safely"
By ZoeyAI · · 7 min read
An AI chatbot for mortgage brokers answers the first questions borrowers ask on your website: do you charge a fee, how does using a broker work, can you help with refinancing, do you work with first home buyers, how do I book a call? Brokers spend much of the day with clients, lenders and paperwork, so website enquiries often wait. And many borrowers start researching in the evening, after work, when nobody is at the desk.
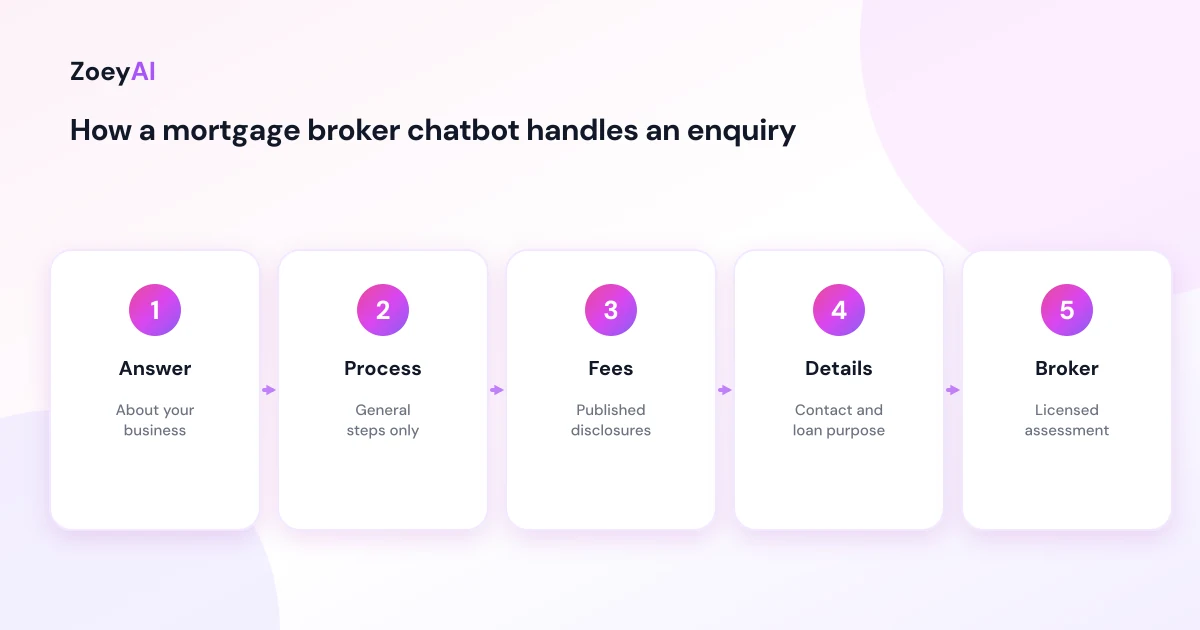
A chatbot can answer general questions about your business straight away, capture a call request with the basics and pass everything that needs judgement to a licensed broker. It must never stray into credit assistance. This guide covers what a broker chatbot should handle, the line it must not cross, and how to set it up so it helps your pipeline without creating compliance risk.
What does an AI chatbot for mortgage brokers actually do?
A well-set-up broker chatbot sticks to four kinds of enquiry:
- About your business. Who you are, the areas and borrower types you work with (for example first home buyers, refinancers, investors or self-employed borrowers), and how to meet you, in person, by phone or by video.
- How the process works. The general steps from first chat to settlement, as you describe them on your website, and the documents you usually ask for.
- Fees and how you are paid. Whether you charge clients a fee and how broker remuneration works, using the disclosure wording you already publish.
- Booking a conversation. Capturing the borrower's name, contact details, the general reason for the enquiry (purchase, refinance, construction, investment) and preferred call times.
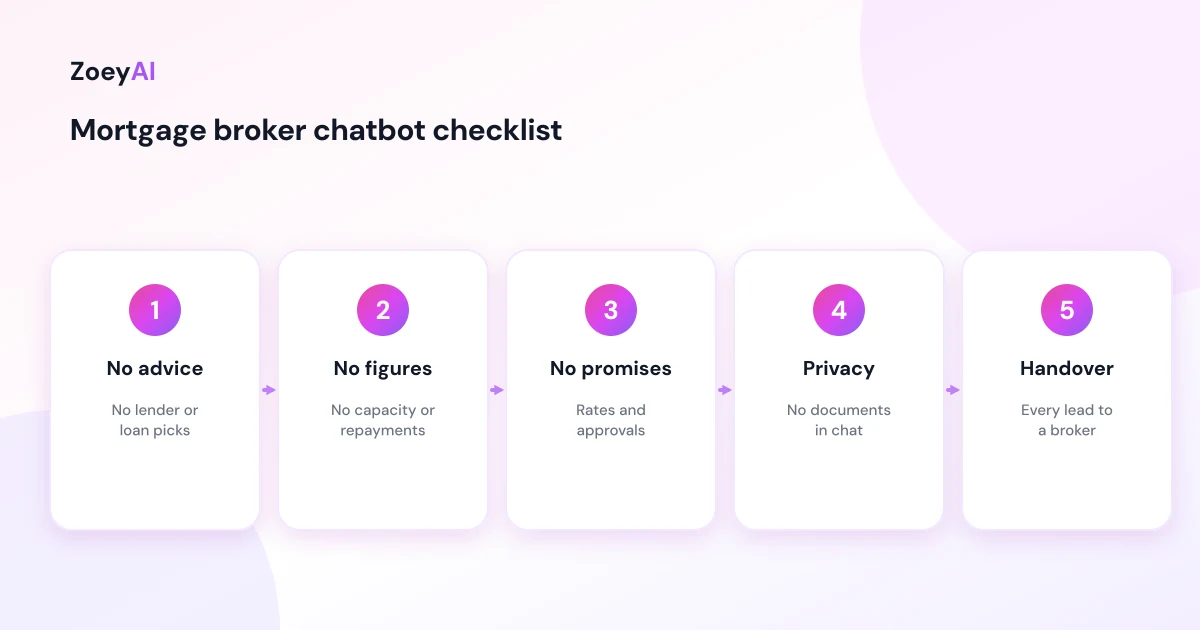
What it should not do is suggest a loan, lender or product, say what someone can borrow, estimate repayments for their situation, or comment on whether they are likely to be approved. Those are for a licensed broker after a proper assessment.
The line a broker chatbot must not cross
Mortgage broking in Australia is regulated under the National Consumer Credit Protection Act 2009, and brokers must hold an Australian credit licence or be authorised as a credit representative. ASIC's Regulatory Guide 273 explains what ASIC looks for when it assesses compliance with the best interests obligations that apply to mortgage brokers.
A website chatbot is not a broker. It has not assessed the borrower's needs, objectives or financial situation, and it is not the person accountable for a recommendation. So the safest design is simple: the chatbot handles information about your business and the next step, and nothing that looks like credit assistance.
In practice, that means the chatbot should not:
- Recommend a lender, loan type or product, even in general terms like "a fixed rate would suit you".
- Quote borrowing capacity or repayment figures based on details the borrower types in.
- Comment on approval chances, credit history or whether a lender will accept their income.
- Quote interest rates as offers. Rates change, depend on the borrower and lender, and are not yours to promise.
When a borrower asks any of these, a good reply acknowledges the question, explains that a broker needs to look at their situation first, and offers to book a call. Write this response with your licensee or compliance adviser, and test it with many different phrasings.
Point borrowers to independent information
Borrowers often want to understand the basics before they talk to anyone. ASIC's Moneysmart website has a plain-English guide to using a mortgage broker, and the same site covers topics such as choosing a home loan and switching lenders. Linking to independent, official information is often more useful, and safer, than having the chatbot explain general credit concepts itself.
Some borrowers also want to check a broker's credentials. ASIC's professional registers include credit licensees and credit representatives. Your chatbot can share your licence or credit representative number exactly as it appears in your website footer or disclosure documents.
Questions a broker chatbot handles well
Typical questions a chatbot can answer from your own content:
- "Do you charge a fee for your service?"
- "How does a mortgage broker get paid?"
- "Do you help with refinancing?"
- "Do you work with self-employed borrowers?"
- "What documents will I need?"
- "Can we meet after hours or by video?"
- "What areas do you cover?"
- "How do I book a call?"
Questions such as "How much can I borrow?" or "Which bank has the best rate?" should get the same response every time: a broker will work that out with you, and here is how to book a time. Our guide on how to write chatbot prompts shows how to set these boundaries clearly in your chatbot's instructions.
What to train a mortgage broker chatbot on
Keep the knowledge base short and approved by your licensee:
- Business details. Names of your brokers, office location, meeting options, hours, phone and email, and your licence or credit representative number as published.
- Who you help. The borrower types and loan purposes you work with, in the same words your website uses.
- Process and documents. Your general process from first meeting to settlement, and the standard document list you already give clients.
- Fees and disclosures. Your published fee position and remuneration disclosure wording, unchanged.
- Booking. Your calendar link, or the details your team needs for a call-back: name, phone, email, loan purpose, rough timeframe and preferred call times.
- A "never do" list. No product, lender or loan type recommendations, no borrowing capacity or repayment estimates, no approval predictions, no rate promises and no requests for sensitive financial documents in chat.
Our guide on how to train an AI chatbot on your website content walks through scanning your site and adding missing answers.
Client information and privacy
Borrowers may volunteer a lot in chat: income, debts, credit problems, family circumstances. Your chatbot should not ask for it. The Privacy Act 1988 and the Australian Privacy Principles may apply to your business, and credit-related information carries extra sensitivity.
Practical rules:
- Collect contact details and the general loan purpose only. Leave income, liabilities and identification for your fact-find process.
- Never ask for payslips, bank statements, tax returns or ID documents in chat.
- Explain in your privacy policy how chat enquiries are stored and who can access them.
- Disclose that the chatbot is an AI. For example: "Hi, I'm the AI assistant for [business]. I can answer questions about how we work and book you a call with a broker. I can't give advice about loans or lenders."
Human handover: every borrower goes to a broker
Route conversations by type:
- Purchase, refinance and construction enquiries to the broker who covers that area or client type.
- Existing client questions (application status, documents, settlement dates) to the broker or support person handling the file.
- Complaints to the person named in your complaints process, with your published internal dispute resolution details.
ZoeyAI lets a broker take over a live conversation from the dashboard on Basic and Pro plans, and business hours settings let the chatbot tell borrowers when the team will reply. Pro adds up to 5 team seats, webhooks to send new enquiries to your CRM and CSV export. Our human handover best practices explain how to make the switch smooth.
How to tell if it is working
Track practical results rather than chat volume:
- Call requests captured, particularly outside office hours
- How quickly brokers follow them up
- How many become fact-finds or applications, tracked in your own CRM
- Questions the chatbot could not answer, so you can add approved content
- Any reply that edged towards advice, found by reading a sample of conversations each week
What it costs
ZoeyAI pricing is in AUD and includes GST. There is a free Starter plan for live chat without AI. AI plans start at $29 a month incl. GST on Basic (100 conversations a month, knowledge base, website scanner, business hours and human takeover) and $79 a month incl. GST on Pro (250 conversations a month, up to 5 team seats, webhooks, CSV export and branding removal). Enterprise pricing is available on request, and every new account starts with a 7-day free trial. See the pricing section for current details.
Frequently asked questions
Can an AI chatbot for mortgage brokers recommend a home loan?
No. Recommending a loan, lender or product is for a licensed broker who has assessed the borrower's situation. The chatbot should answer questions about your business and book a call.
Can the chatbot tell borrowers how much they can borrow?
It should not. Borrowing capacity depends on a full assessment and the lender's criteria. The chatbot can link to Moneysmart's general information and offer to book a time with a broker.
Is it safe for a chatbot to quote interest rates?
Avoid it. Rates change and depend on the borrower and lender. Keep the chatbot to your services, process and published fee information.
What details should the chatbot collect?
Name, phone, email, the general loan purpose, a rough timeframe and preferred call times. Financial documents and detailed income or debt information belong in your fact-find, not in chat.
Should the chatbot say it is an AI?
Yes. A clear greeting that says it is an AI assistant and cannot give advice about loans sets the right expectations from the first message.
Will a chatbot replace a broker?
No. It answers routine questions and captures enquiries when you are with clients or out of the office, so brokers spend their time on conversations that need their expertise.
Keep reading
"AI Chatbot for Event Venues: Answer Capacity and Package Questions and Capture Enquiries"
How an AI chatbot for event venues answers questions about spaces, capacity, published packages and policies, captures wedding, corporate and party enquiries with the right details, treats dates as requests rather than bookings and hands every lead to your events team.
"AI Chatbot for Funeral Homes: Calm Answers and a Fast Path to Your Staff"
How an AI chatbot for funeral homes answers practical questions about services, published prices and what to do first, uses a calm and respectful tone, never pressures families, protects privacy and connects people with your staff quickly, including after hours.